What “Paid in Full” Really Means in a Timeshare Contract
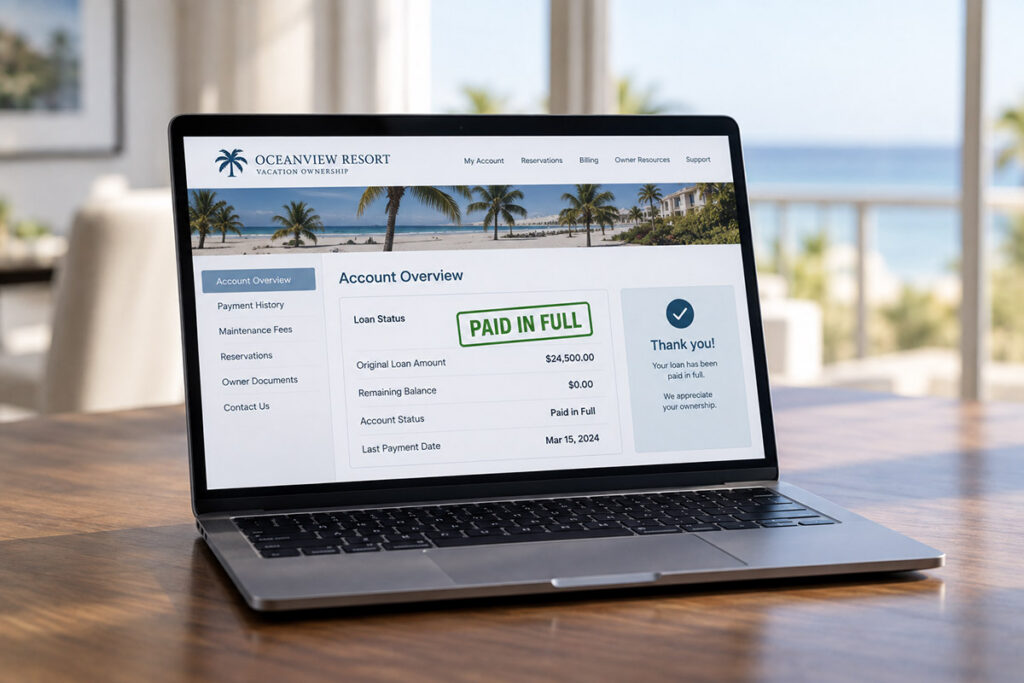
There can be a tremendous sense of relief when a timeshare owner finally makes the last payment on a purchase loan. After years of monthly payments, the balance reaches zero. The statement says PAID IN FULL. The financing that once accompanied the purchase is finally behind you.
But what exactly has been paid in full?
For many timeshare owners, this is where an important misunderstanding begins. Paying off the loan used to purchase a timeshare generally does not mean the timeshare ownership itself has ended.
The owner may no longer owe money on the original purchase financing, but the deed, membership, points interest, trust interest, or right-to-use arrangement may remain. So can maintenance fees, association obligations, assessments, and other responsibilities associated with the ownership.
Understanding that difference becomes particularly important for owners who have paid for their timeshare but no longer want it.
The Loan and the Timeshare Ownership Are Two Different Things
Think back to the original purchase. A buyer may have agreed to purchase a timeshare for $25,000 and financed most of that amount. The financing created an obligation to repay the money borrowed for the purchase.
The timeshare itself created something different: an ownership or contractual relationship with the resort, association, trust, club, or vacation program.
When the final loan payment is made, the financing obligation may be satisfied. The underlying timeshare interest does not necessarily disappear with it.
For a deeded timeshare, the owner may still hold title to the real estate interest. A points owner may still hold an interest governed by club, trust, or program documents. A right-to-use owner may remain subject to an agreement that continues for a particular term.
This is why the phrase “paid in full” needs context. It may tell you the balance on a loan. It does not necessarily tell you the status of the timeshare.
What Actually Changes When the Timeshare Loan Is Paid Off?
Paying off the financing is still significant. The owner no longer has the recurring payment associated with that loan. Depending on the financing arrangement and type of ownership, a lien securing the debt may also be released or satisfied.
What does not necessarily change is everything connected to continued ownership. An owner may still receive annual maintenance-fee bills. The association may still impose properly authorized assessments. Reservation and usage rules may still apply. A deeded interest may remain titled in the owner’s name.
That is the key point:
The absence of a timeshare loan balance does not necessarily mean the absence of an ownership obligation.
Owners who are unsure of their status should look beyond the final loan statement and determine exactly what interest they continue to hold.
Why Maintenance Fees Can Continue After the Loan Is Gone
This is often the part that surprises owners most. Someone may have spent ten years paying for a timeshare and reasonably think, “I finally own it outright. Why am I still receiving bills?”
Because timeshare maintenance fees generally serve a different purpose from the purchase loan.
The purchase loan financed the acquisition. Maintenance fees may fund the ongoing expenses associated with operating and maintaining the property or vacation program, including items such as management, repairs, insurance, reserves, utilities, staffing, and other expenses. Those obligations are typically governed by the ownership and association documents rather than the remaining balance on the original financing.
As a result, an owner can have no timeshare loan at all and still have continuing financial obligations associated with ownership.
Special assessments may present another expense. Whether an assessment is permitted, how it must be approved, and how it is allocated depend on the governing documents and applicable law. This is why owners should not treat the final loan payment as the point when all future timeshare expenses automatically stop.
“Paid Off” Is Not the Same as “No Longer the Owner”
A simpler way to understand the issue is to separate debt from ownership.
Consider a conventional home. Paying off the mortgage does not mean the homeowner stops owning the house. Property taxes, insurance, maintenance, and association expenses may continue because the property is still owned. A timeshare is different in many important ways, but the same basic concept helps explain why the words “paid in full” can be misleading.
The debt can end while the ownership continues.
With a deeded timeshare, one of the most important questions is whether the deed remains in the owner’s name. With other types of timeshare interests, the relevant question may involve the membership, trust, points program, or right-to-use agreement.
The name of the program matters less than understanding the legal structure behind it. If you are still the owner or member, paying off the purchase price may not have ended the relationship.
Can a Paid-Off Timeshare Still Become a Collection Problem?
Potentially, yes.
An owner may have no remaining purchase loan but later fall behind on maintenance fees or assessments. Depending on the ownership, governing documents, applicable law, and reporting practices involved, unpaid obligations can potentially result in collection activity or other enforcement.
A deeded timeshare may also involve lien and foreclosure rights associated with unpaid assessments, depending on the applicable documents and state law.
That creates a situation some owners do not anticipate. They may have spent years successfully paying off the original purchase only to encounter a new financial problem after they stop paying maintenance fees.
For that reason, simply stopping payment should not be confused with ending the timeshare.
Before intentionally allowing an account to become delinquent, an owner should understand what is owed, why it is owed, what enforcement rights may exist, and whether another option is available.
What About Timeshares That Continue for Decades?
Some timeshare ownership interests are designed to last for very long periods. Certain deeded interests may not have a conventional expiration date, while other programs may have specific terms, renewal provisions, or termination procedures.
This is sometimes described broadly as a timeshare existing “in perpetuity,” but owners should look at their actual documents rather than assuming every timeshare works the same way.
The important question is how and when this particular ownership ends.
Does the deed continue until the interest is transferred? Does the membership have a defined term? Are there surrender provisions? Does the association or developer offer a voluntary return program? What do the governing documents say about termination?
Those questions become increasingly important as owners get older or begin thinking about estate planning.
Your Timeshare Is Paid Off. But Is the Ownership Over?
If the loan balance is zero but maintenance fees and other obligations continue, Finn Law Group can review the ownership documents and help you understand what you still own and what options may be available.
Call 727-214-0700 or schedule a free consultation.
What Happens to a Paid-Off Timeshare When the Owner Dies?
This is another area where owners should be careful with broad statements.
A paid-off timeshare may still be an asset or interest that must be addressed as part of an owner’s estate. But that does not mean every family member automatically becomes personally responsible for the timeshare simply because a parent or relative owned it.
The answer can depend on the form of ownership, title, estate documents, probate law, whether someone accepts or disclaims an inheritance, and the law of the applicable jurisdiction. That is why estate questions should be addressed before assumptions are made about what children or other family members “have to” inherit.
For an older owner who no longer uses the timeshare, this may be an appropriate time to review the ownership documents and determine how the interest fits into the broader estate plan.
The fact that the purchase loan has already been paid can make the ownership easier to misunderstand. There may be no mortgage statement arriving each month, but the underlying interest may still need to be addressed.
If You No Longer Want the Timeshare, Start With the Developer
A paid-off owner who simply no longer wants the timeshare does not necessarily need to begin with litigation or a third-party exit service. Start by determining whether the developer, association, or vacation program has a voluntary surrender, deed-back, or owner-relief program.
Some programs may accept certain ownership interests back if eligibility requirements are satisfied. Others may impose conditions involving account status, financing, maintenance fees, or the type of ownership involved.
A paid-off account can sometimes be important because the absence of purchase financing may remove one potential obstacle to a voluntary return. But policies vary significantly. Ask for the program requirements in writing and understand what documentation will establish that the ownership has actually ended.
Most importantly, do not assume the timeshare is gone merely because someone says a request has been submitted or is being processed.
The completion documents matter.
When a Paid-Off Timeshare Becomes a Legal Question
There is an important difference between an owner who simply no longer wants a timeshare and an owner who believes there is a legal problem with the ownership.
The second situation may involve disputed sales representations, financing history, disclosure concerns, upgrades, changes in the ownership program, contract terms, or a developer’s refusal to address an issue the owner believes is legally significant.
At that point, the question becomes more than, “How do I give this back?”
It becomes “What are my legal rights under these documents and circumstances?”
A timeshare cancellation law review can examine the purchase documents, deed or membership structure, sales history, amendments, financing, and other information relevant to the ownership.
That review does not mean every paid-off timeshare can be canceled. Nor does it mean every unwanted ownership presents grounds for litigation.
It means the legal strategy should follow the facts.
Why Legal Review Is Different from an Exit Process
Owners searching for help with a paid-off timeshare may encounter law firms, exit companies, transfer companies, resale businesses, and other services.
They are not interchangeable.
A non-law-firm exit company cannot independently practice law, provide legal advice, determine an owner’s legal rights as counsel, or represent an owner in court. Some businesses may provide administrative, negotiation, or transfer services, but that is different from legal representation.
A licensed attorney can examine the documents and facts to determine whether a legal issue exists, advise the owner about available rights and risks, communicate as legal counsel, and pursue appropriate remedies where supported by the facts and law.
Finn Law Group explains this further in its discussion of why hiring a law firm differs from working with an exit company.
Not every paid-off owner needs an attorney. If a legitimate developer surrender program resolves the ownership cleanly, that may be an appropriate solution.
But when the problem involves the contract, disputed representations, title, assessments, or other legal rights, an exit process and legal representation are not the same service.
How Finn Law Group Reviews a Paid-Off Timeshare
Finn Law Group begins with a straightforward question:
What does the owner still own?
That may require reviewing the original purchase agreement, deed, financing documents, club or trust documents, association materials, upgrades, maintenance-fee statements, and correspondence with the developer.
The next question is what the owner wants to accomplish.
For some people, the concern is simply ending an ownership they no longer use. For others, the review may uncover questions involving how the timeshare was sold, how it changed over time, or what rights and obligations currently exist.
Frequently Asked Questions
Does paying off my timeshare loan cancel my timeshare?
Generally, no. Paying the loan balance satisfies the financing obligation. The underlying deed, membership, points interest, trust interest, or right-to-use arrangement may continue separately.
Will maintenance fees stop when my timeshare is paid in full?
Not necessarily. Maintenance fees are generally associated with continuing ownership or membership rather than the balance of the original purchase loan. Review the governing documents to determine what obligations remain.
Can I stop paying maintenance fees once the loan is paid off?
Paying off the purchase loan does not automatically eliminate maintenance-fee obligations. Nonpayment may lead to collection or other enforcement depending on the ownership, governing documents, and applicable law. Understand the consequences before stopping payment.
Can I give a paid-off timeshare back to the developer?
Possibly. Some developers or programs offer voluntary surrender, deed-back, or owner-relief options for qualifying ownerships. Eligibility requirements vary, so owners should contact the developer and obtain the requirements in writing.
Will my children automatically inherit my paid-off timeshare?
Not necessarily. Estate and inheritance issues depend on the ownership structure, title, estate planning, probate law, and other circumstances. Family members should not assume they automatically become personally responsible for an ownership simply because a relative dies.
Is a paid-off timeshare easier to exit?
It can remove the issue of an outstanding purchase loan, but it does not guarantee that a developer will accept the ownership back or that another exit option exists. The ownership documents and individual circumstances still matter.
Additional information is available in Finn Law Group’s timeshare attorney FAQs.
Paid in Full May Be the End of the Loan, Not the Timeshare
Seeing a zero balance is an accomplishment. But owners should understand exactly what that zero represents.
A paid-off loan and an ended timeshare ownership are not necessarily the same thing.
If your name remains on a deed, membership, trust interest, or other timeshare arrangement, obligations associated with that ownership may continue even though the purchase financing is long gone.
If you no longer want the timeshare, start by identifying exactly what you own and contacting the developer or program to determine whether a legitimate surrender option exists. If the documents, sales history, assessments, or other circumstances raise legal questions, then an attorney can evaluate whether additional options may be available.
The goal is not simply to stop receiving bills.
It is to understand when the financial obligation has actually ended and when the ownership itself has legally come to an end.
About Finn Law Group
Finn Law Group is a timeshare law firm focused on representing consumers in timeshare-related matters. From its Florida headquarters, the firm works with owners confronting complex contracts, disputed sales representations, cancellation concerns, developer disputes, and other legal issues arising from timeshare ownership.
The firm’s practice begins with legal analysis rather than a standardized exit process. Attorneys review the ownership documents, sales history, applicable law, and individual circumstances before advising a client about available options. Where supported by the facts and law, representation may include negotiation, dispute resolution, or litigation.
To discuss a paid-off timeshare and understand what obligations may remain, call 727-214-0700 or schedule a free consultation.
Disclosure
This article is provided for informational purposes only and should not be considered legal advice. Every timeshare dispute and consumer protection matter is unique and depends on the specific facts and applicable law. Paying off timeshare financing does not, by itself, determine whether an ownership, membership, deed, or other legal interest has ended. Maintenance obligations, transfer rights, estate issues, surrender programs, and potential legal remedies vary by ownership structure and jurisdiction. If you have questions about your legal rights or are considering taking action regarding your timeshare, consult with a licensed attorney experienced in consumer protection and timeshare law before making important legal or financial decisions.
| Not Sure What Your Paid-Off Timeshare Contract Still Requires? Paying off the loan is only part of the picture. Our attorneys can review your contract and explain what obligations remain and what your legal options are. Call 727-214-0700 |